Report, 15 pages
Department of Labor financial and compliance audit (draft), contracts 1988–1990
March 23, 1992
The Department of Labor's Independent Audit Bureau sends Coordinator Brett Mair a draft audit of the Coalition's first two health and safety contracts (July 1988 – June 1990). Auditors found the program in general compliance but questioned $4,505.77: costs shared among programs without a documented allocation plan, fringe benefits reported incorrectly, three months of rent misallocated, and no clear audit trail from the books to the vouchers. The report gives the scope, background, opinion, internal controls, findings and recommendations, and the cash and expenditure schedules for each contract.
The page reading “-5-” is nearly blank. A second photograph of Auditor's Exhibit I-C is not shown. Exhibits I-A and I-B, which itemize two staff members' wages and benefits, are withheld.
Download or cite this itemPages
 (open zoom view)
Read the page text (machine-read, mostly readable)
This text was generated automatically from the photograph and has not been corrected. The image is the authoritative record.
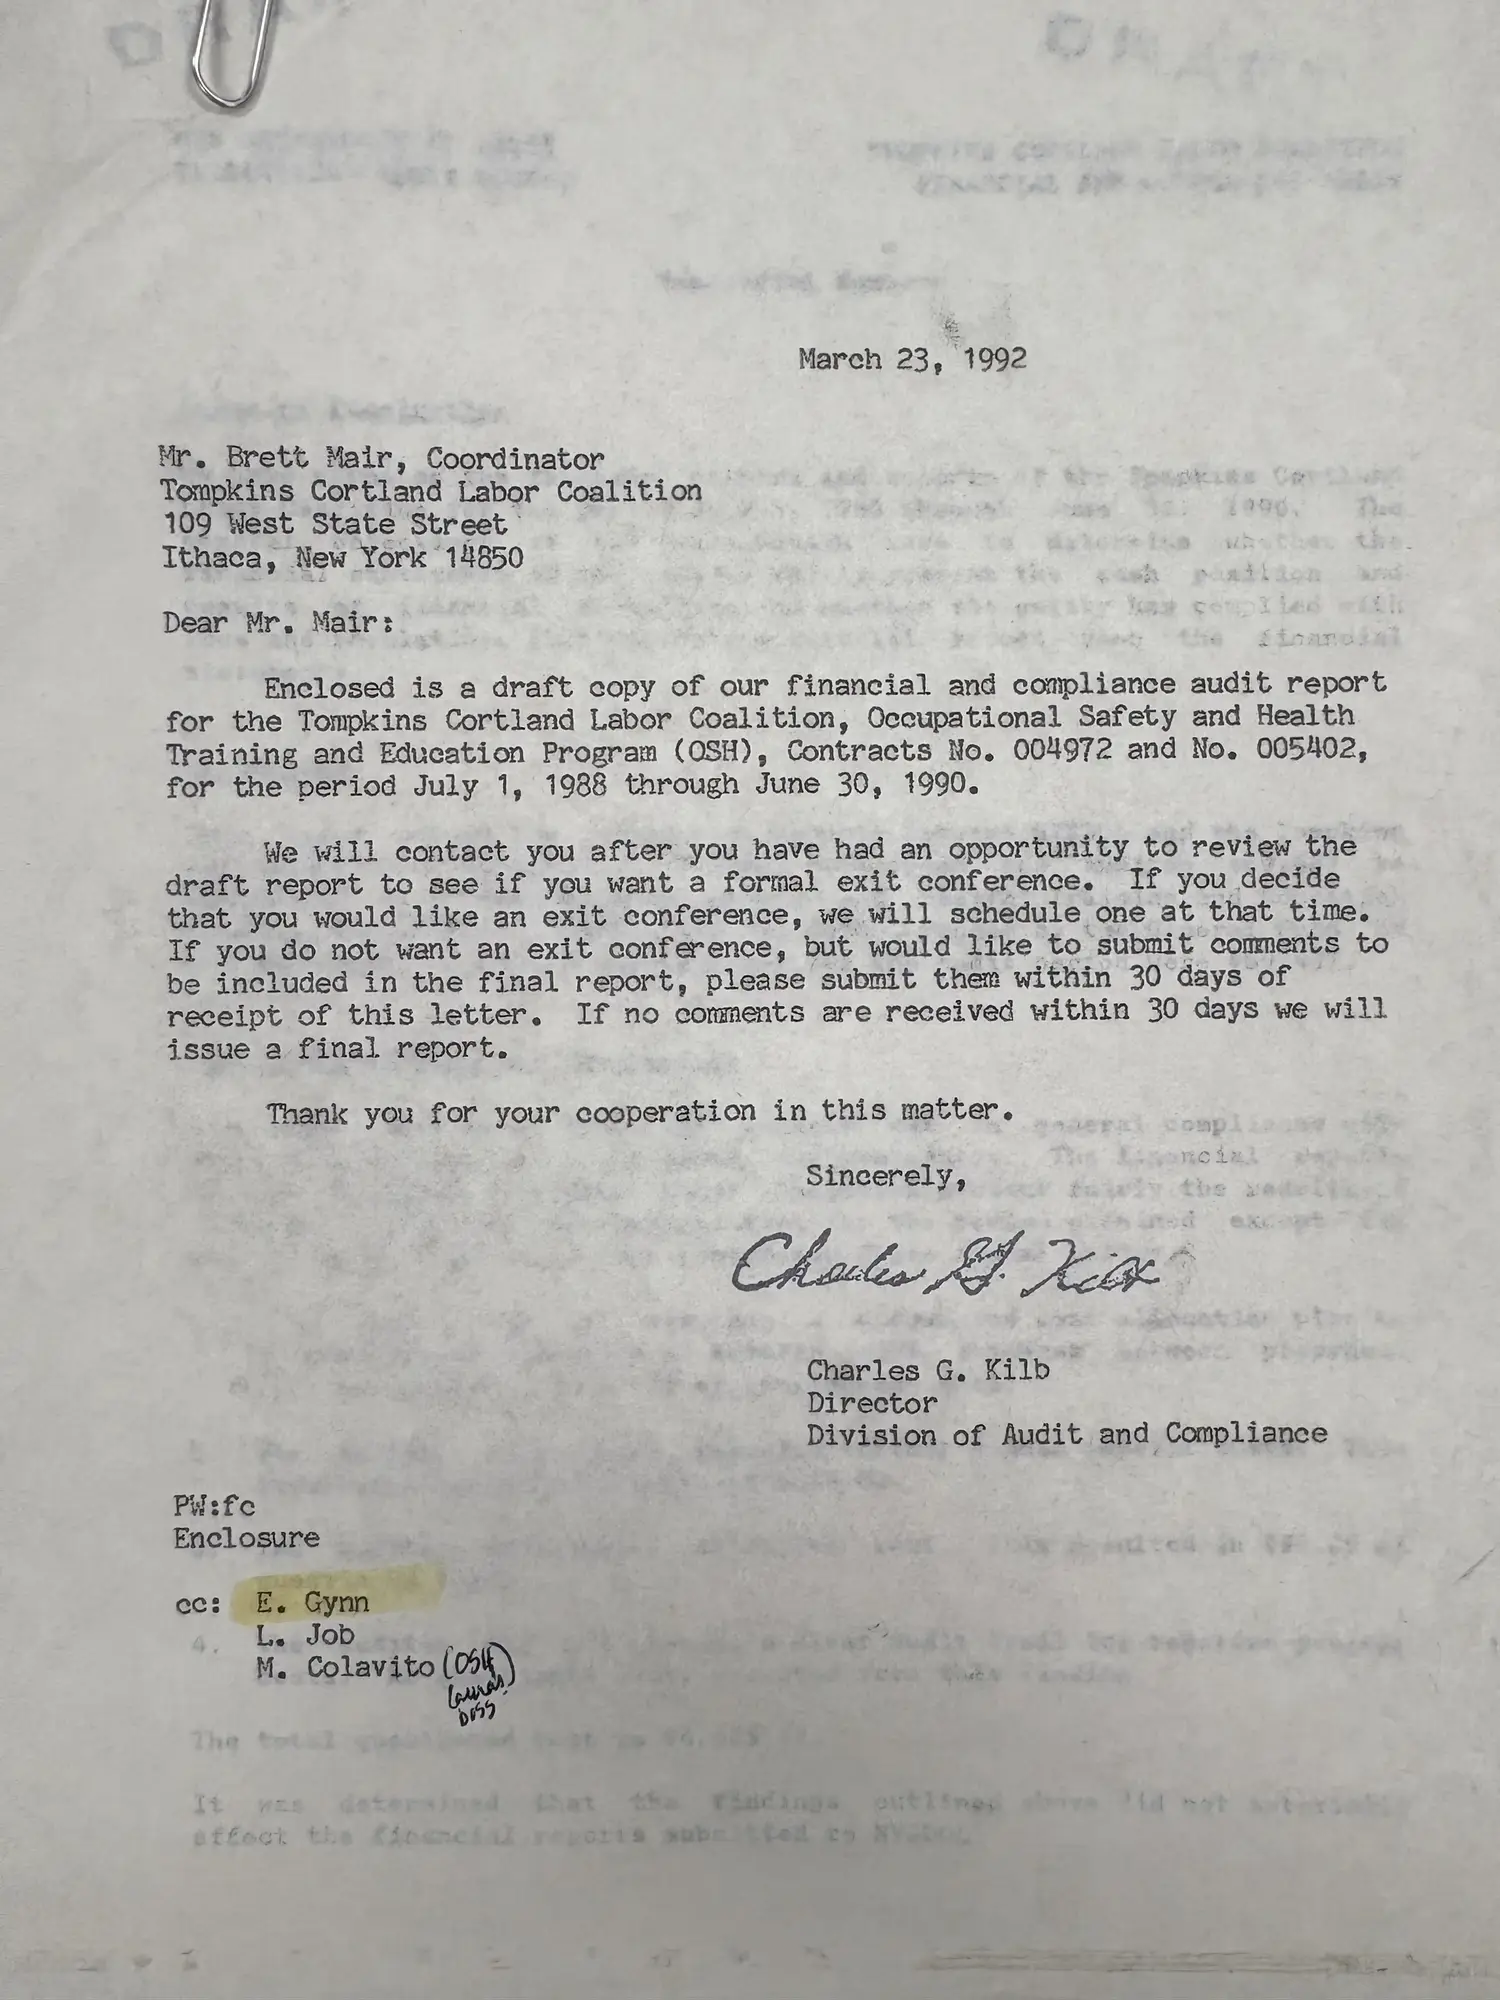
March 23, 1992

Mr. Brett Mair, Coordinator
Tompkins Cortland Labor Coalition
109 West State Street
Ithaca, New York 14850

Dear Mr. Mair:

Enclosed is a draft copy of our financial and compliance audit report
for the Tompkins Cortland Labor Coalition, Occupational Safety and Health
Training and Education Program (OSH), Contracts No. 004972 and No. 005402,
for the period July 1, 1988 through June 30, 1990.

We will contact you after you have had an opportunity to review the
draft report to see if you want a formal exit conference. If you decide
that you would like an exit conference, we will schedule one at that time.
If you do not want an exit conference, but would like to submit comments to
be included in the final report, please submit them within 30 days of
receipt of this letter. If no comments are received within 30 days we will
issue a final report.

Tnank you for your cooperation in this matter.

Sincerely,

Chak Eb hig!

Charles G. Kilb
Director
Division of Audit and Compliance

Pusfe
Enclosure
 (open zoom view)
Read the page text (machine-read, mostly readable)
This text was generated automatically from the photograph and has not been corrected. The image is the authoritative record.
PARTMENT OF LABOR TOMPKINS CORTLAND LABOR COALITION
ENDENT AUDIT BUREAU FINANCIAL AND COMPLIANCE AUDIT

Managerial Summary

Scope of Examination

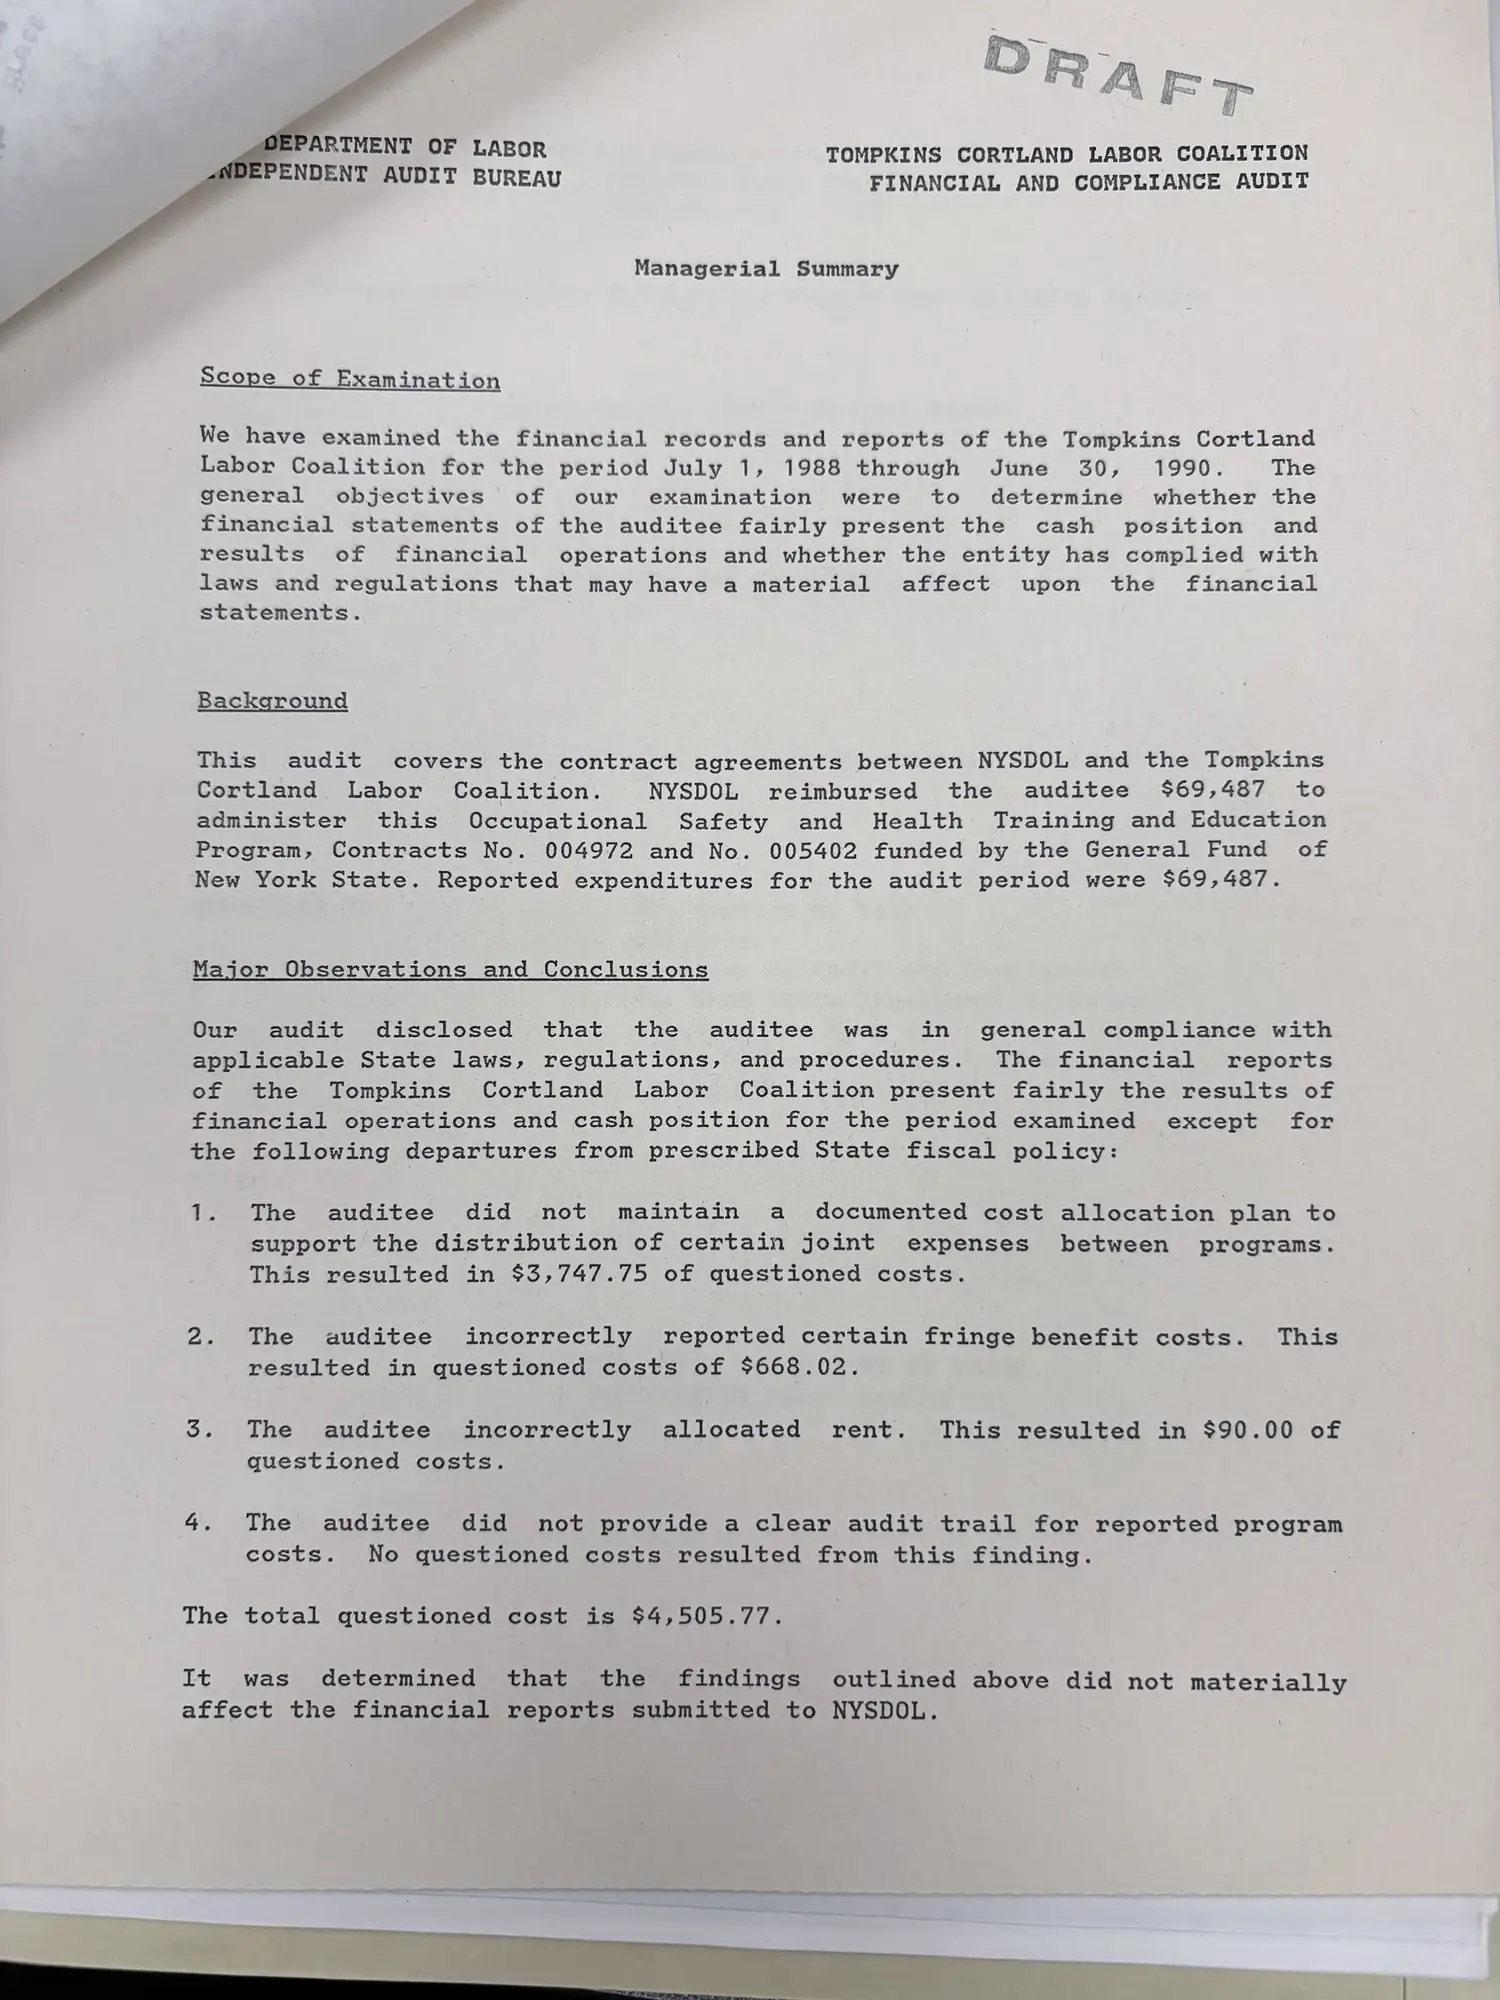
We have examined the financial records and reports of the Tompkins Cortland
Labor Coalition for the period July 1, 1988 through June 30, 1990. The
general objectives of our examination were to determine whether the
financial statements of the auditee fairly present the cash position and
results of financial operations and whether the entity has complied with
laws and regulations that may have a material affect upon the financial
statements.

Background

This audit covers the contract agreements between NYSDOL and the Tompkins
Cortland Labor Coalition. NYSDOL reimbursed the auditee $69,487 to
administer this Occupational Safety and Health Training and Education
Program, Contracts No. 004972 and No. 005402 funded by the General Fund of
New York State. Reported expenditures for the audit period were $69,487.

Major Observations and Conclusions

Our audit disclosed that the auditee was in general compliance with
applicable State laws, regulations, and procedures. The financial reports
of the Tompkins Cortland Labor Coalition present fairly the results of
financial operations and cash position for the period examined except for
the following departures from prescribed State fiscal policy:

1. The auditee did not maintain a documented cost allocation plan to
support the distribution of certain joint expenses between programs.
This resulted in $3,747.75 of questioned costs.

2. The auditee incorrectly reported certain fringe benefit costs. This
resulted in questioned costs of $668.02.

3. The auditee incorrectly allocated rent. This resulted in $90.00 of
questioned costs.

4. The auditee did not provide a clear audit trail for reported program
costs. No questioned costs resulted from this finding.

The total questioned cost is $4,505.77.

It was determined that the findings outlined above did not materially
affect the financial reports submitted to NYSDOL.
 (open zoom view)
Read the page text (machine-read, mostly readable)
This text was generated automatically from the photograph and has not been corrected. The image is the authoritative record.
Tompkins Cortland Labor Coalition
109 West State Street
Ithaca, N.Y. 14850

nal Safety and Health Training and Education Program

Contracts No. 004972 and No. 005402

FINANCIAL AND COMPLIANCE AUDIT

FOR THE PERIOD July 1, 1988 THROUGH June 30, 1990

SUBMITTED TO: é Mr. Charles G. Kilb

j Director ’
Division of Audit and Compliance
New York State Department of Labor
Building 12, Room 261
State Office Building Campus
Albany, New York 12240

DATE:
 (open zoom view)
Read the page text (machine-read, contains errors)
This text was generated automatically from the photograph and has not been corrected. The image is the authoritative record.
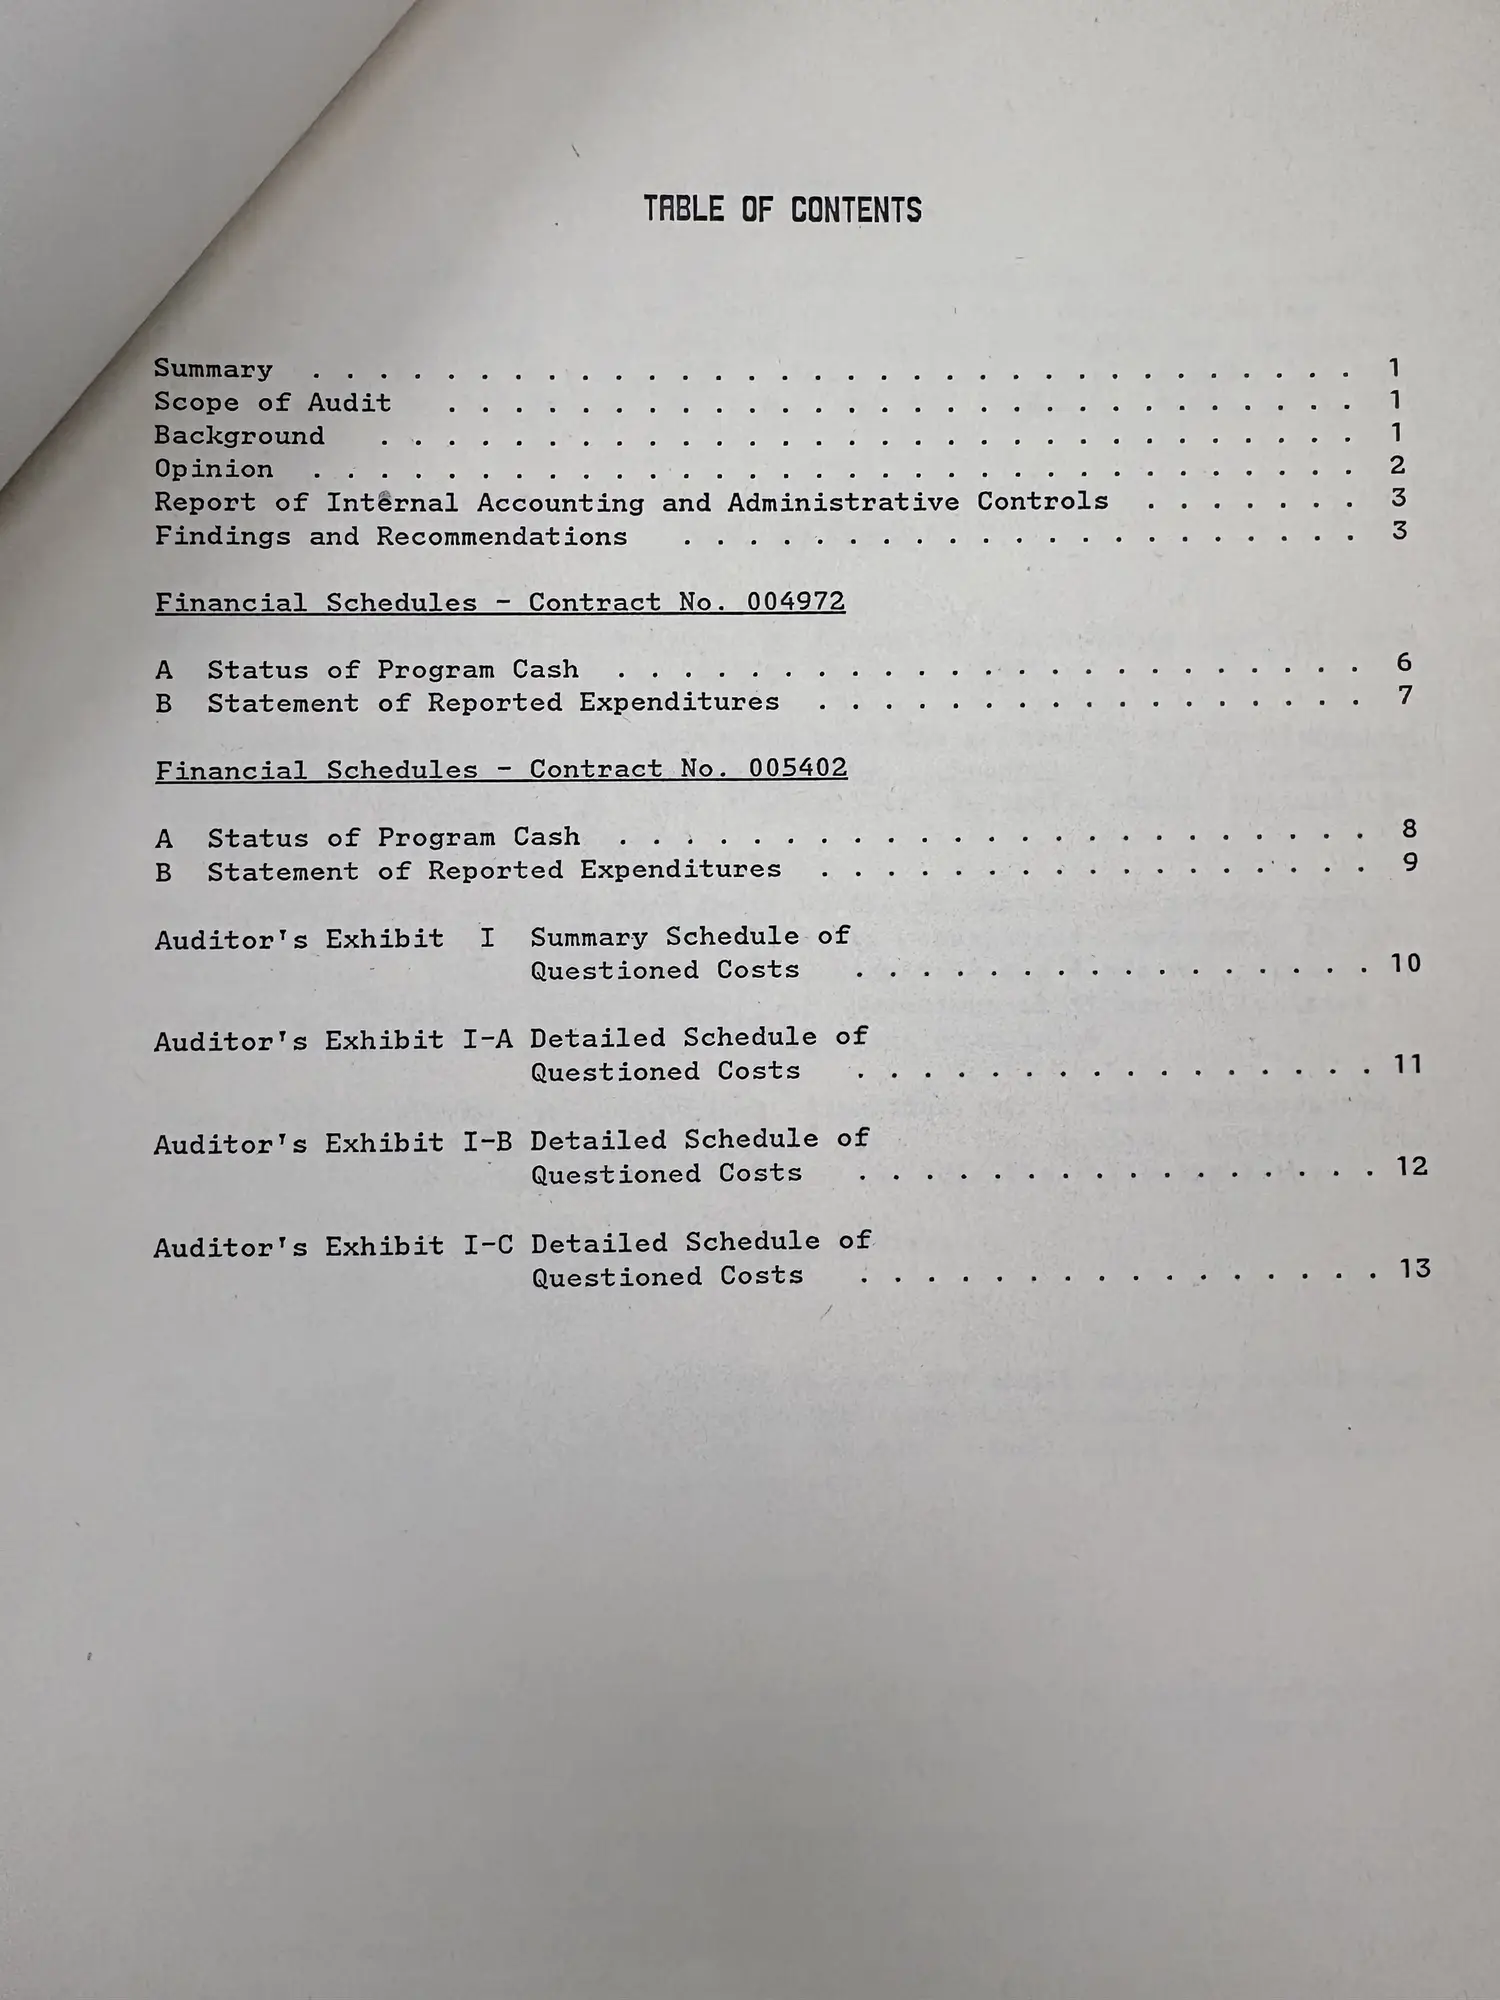
TABLE OF CONTENTS

Summary
Scope of Audit
Background
Opinion

Findings and Recommendations
Financial Schedules —- Contract No. 004972

A Status of Program Cash ae
B Statement of Reported Pepe nadeue eee

Financial Schedules - Contract No. 005402

A Status of Program Cash uae
B Statement of Reported Eepcn aie eee

Auditor's Exhibit I Summary Schedule of
d Questioned Costs

Auditor's Exhibit I-A Detailed Schedule of
Questioned Costs

Auditor's Exhibit I- -B Detailed Schedule of
Questioned Costs

Auditor's Exhibit I-C Detailed Schedule of
Questioned Costs

Report of imcernal Pesounting’ ea UNawundetwotive Gontpols
 (open zoom view)
Read the page text (machine-read, mostly readable)
This text was generated automatically from the photograph and has not been corrected. The image is the authoritative record.
SUMMARY

e have examined Schedules A and B which summarize reported cash position
and financial results of the Occupational Safety and Health Training and
Education Program (OSH), Contracts No. 004972 and No. 005402 for the period
July 1, 1988 through June 30, 1990. These contracts were awarded by the

New York State Department of Labor to the Tompkins Cortland Labor
Coalition.

SCOPE OF AUDIT

This report covers our examination of financial transactions, accounts and
reports for the period July 1, 1988 to June 30, 1990.

Our examination was made in accordance with the provisions of the Standards
for Audit of Governmental Organizations, Programs, Activities and

Functions, promulgated by the Comptroller General, which pertain to
financial and compliance audits.

Our examination included such tests of the accounting and program records
and such other auditing procedures as we considered necessary in the
circumstances. The aforementioned Schedules A and B are not intended to
present either the financial results of operations or financial position in
conformity with generally accepted accounting principles.

This audit covered all activities, functions, etc., which may have had a
material effect on the financial statements of the audited entity. The
audit of compliance management practices included the following areas:

- Financial Control and Accounting Systems
- Allowability of Costs
- Limitations on Costs

We have used judgmental sampling to test the audit universe as universe
sizes were too small to employ statistical sampling techniques. The total
expenditures for the period were $69,487. Our audit sample totalled
$21,174 or 31% of the total expenditures.

BACKGROUND

This audit was made in accordance with the general provisions of the New
York State OSH Legislation and the auditee's contract agreements with
NYSDOL. It covered the period July 1, 1988 through June 30, 1990.

The audit covers the contract agreements between NYSDOL and the Tompkins
Cortland Labor Coalition to operate an Occupational Safety and Health
Training and Education Program. The goal of the program is to promote safe
and healthy conditions in the workplace. This is to be achieved through
training, education, and other proven preventive programs designed to:

HAB IE -1U04 (3-03)
 (open zoom view)
Read the page text (machine-read, mostly readable)
This text was generated automatically from the photograph and has not been corrected. The image is the authoritative record.
abate occupational safety and health hazards in the workplace;

encourage voluntary compliance

with occupational safety and
health regulations; and

foster activities on the part of employers and employees
intended to prevent workplace injuries and illnesses.

The goals and objectives of these contract agreements were to:

~ assist and educate workers in identifying the hazards associated
with their occupations and

= increase labor and management efforts to reduce health and safety
risks at the worksite.

This was accomplished through surveys, group interviews, training

workshops, and establishing a Health and Safety Committee. The specific
areas of concern were:

- hazardous substances related to custodial occupations in both
contracts

- asbestos in Contract No. 004972 and
= video display terminals in Contract No. 005402.

The general objectives of this financial and compliance audit are to
determine whether:

1. financial operations are properly conducted;
2. ‘financial reports of an audited entity are fairly presented; and

3. the entity has complied with applicable laws and regulations.
OPINION

Auditor’s Exhibit I lists $4,505.77 of questioned costs disclosed by our
audit sampling for the period July 1, 1988 to June 30, 1990. The
determination as to whether the costs will be allowable or unallowable will
be made by the New York State Department of Labor.

In our opinion, subject to any effects of the ultimate resolution of
questioned costs, Schedules A and B_ present fairly the auditee's cash
position and financial results of operations for Contracts No. 004972 and
No. 005402.

HAB IE -104 (3-84)
 (open zoom view)
Read the page text (machine-read, mostly readable)
This text was generated automatically from the photograph and has not been corrected. The image is the authoritative record.
Pi cral for financial and compliance audits contained in the U.S.

aa Account ing Office's Standards for Audit of Governmental
eveissations: Proarans, Activities and Functiong) > The pepo ae
peouvaeion are to establish a basis for reliance on the system of internal

n determining the nature, timing and
extent of other auditing procedures that are necessary for expressing an
Opinion on the financial statements and to assist us in

performing our examination of the financial statements.

planning and

The objective of internal accounting and administrative control is to
provide reasonable, but not absolute, assurance as to the safeguarding of
assets against loss from unauthorized use or disposition, and the
reliability of financial records for preparing financial statements and
maintaining accountability for assets. The concept of reasonable assurance
recognizes that the costs of a system of control should not exceed the
benefits derived and also recognizes that the evaluation of these factors
necessarily requires estimates and judgments by management.

There are inherent limitations that should be recognized in considering the
potential effectiveness of any system of internal and administrative
accounting control. In the performance of most control procedures, errors
can result from misunderstanding of instructions, mistakes of judgment,
carelessness or other personal factors. Control procedures whose
effectiveness depends upon segregation of duties can be circumvented by
collusion. Similarly, control procedures can be circumvented intentionally
by management with respect to the estimates and judgments required in the
preparation of financial statements.

Further, projection of any evaluation of control to future periods is
subject to the risk that the procedures may become inadequate because of
changes in conditions and that the degree of compliance with the procedures
may deteriorate.

Our study and. evaluation made for the limited purposes set forth in the
first paragraph of this report would not necessarily disclose all material
weaknesses in the system nor all deviations from prescribed compliance
requirements because it was based on selective tests of accounting records
and related data. Accordingly, we do not express an opinion on the system
of internal accounting control. However, our study and evaluation
disclosed no condition that we believe to be a material weakness.

FINDINGS AND RECOMMENDATIONS

1. Our audit disclosed that the Tompkins Cortland Labor Coalition did not
maintain a documented cost allocation plan to support the distribution
of telephone, office supplies, postage and the bookkeeper's wage and
fringe between programs. Without a documented allocation system, the

HAB TE -104 (3-89) : —S— =
 (open zoom view)
Read the page text (machine-read, mostly readable)
This text was generated automatically from the photograph and has not been corrected. The image is the authoritative record.
fairness of t . . -

MMe other peuntaa ac uion of the expenses between these contracts

ed on cur See Sources could not be readily verified. However,

Met for the Rees of oie: staffing and funding, we determined that

etnianl feccrisd eeper 2 wage and fringe in Contract No. 005402, the

$3,211.52 and Pete fair and reasonable. The bookkeeper'’s wages of
n associated fringe benefit costs of $536.23 are

questioned. The total i SOV Lal al s
Exhibit I questioned costs i 35 eh i k
te s is 5 See Auditor

We recommend that the

: Tompkins Cortland Labor Coalition develop and
implement controls

, and procedures to support and document the
allocation of expenditures among various funding sources. The controls
and procedures should clearly define the basis for allocation. The
application of this basis should be uniform and consistent.

Our audit disclosed that the Tompkins Cortland Labor Coalition
incorrectly reported certain fringe benefit costs in Contract No.
005402. Based on our analysis of the actual fringe benefit billings,
we determined that FUTA and disability insurance were underreported and
health insurance was overreported. This resulted in questioned costs
of $668.02. See Auditor’s Exhibit I-B for details.

We recommend that the Tompkins Cortland Labor Coalition report fringe
benefit costs based on actual expenditures per current policies and
billings. In addition, the fringe benefit costs reported should be
restricted to the wage allocation percentages of the staff.

Our audit disclosed that the Tompkins Cortland Labor Coalition
incorrectly allocated rent. The rent expense for three months was
misallocated to the contract. This misallocation totalled $90.00 and
is questioned. See Auditor's Exhibit I-C for details.

We recommend that the Tompkins Cortland Labor Coalition implement
procedures to ensure all costs are properly allocated and reported.

Our audit disclosed that the Tompkins Cortland Labor Coalition did not

provide a clear audit trail for reported program expenditures. The
official books of entry were monthly financial reports which summarized
the entire agency’s checkbook activity. There were no worksheets

provided to reconcile the contract's expenses recorded on the official
books with the expenditures reported on the reimbursement vouchers
‘submitted to NYSDOL. Due to the lack of reconciliation procedures, it
is possible that not all program costs were reported.

Based on our analysis of the contract budget, payroll register and
invoices, we determined the costs reported on the reimbursement
vouchers to be reliable. As a result, the vouchers were used as the
basis for our audit. From our analysis of vouchered amounts, no
material discrepancies were disclosed.

We recommend that the Tompkins Cortland Labor Coalition develop and
implement controls and procedures that would provide a clear audit
trail from the official books of entry to the reimbursement vouchers
submitted to NYSDOL. This system should provide a reconciliation of
 (open zoom view)
Read the page text (machine-read, mostly readable)
This text was generated automatically from the photograph and has not been corrected. The image is the authoritative record.
the

official books of entry with the reimbursement vouchers to ensure
Pall

allowable program costs are reported.
 (open zoom view)
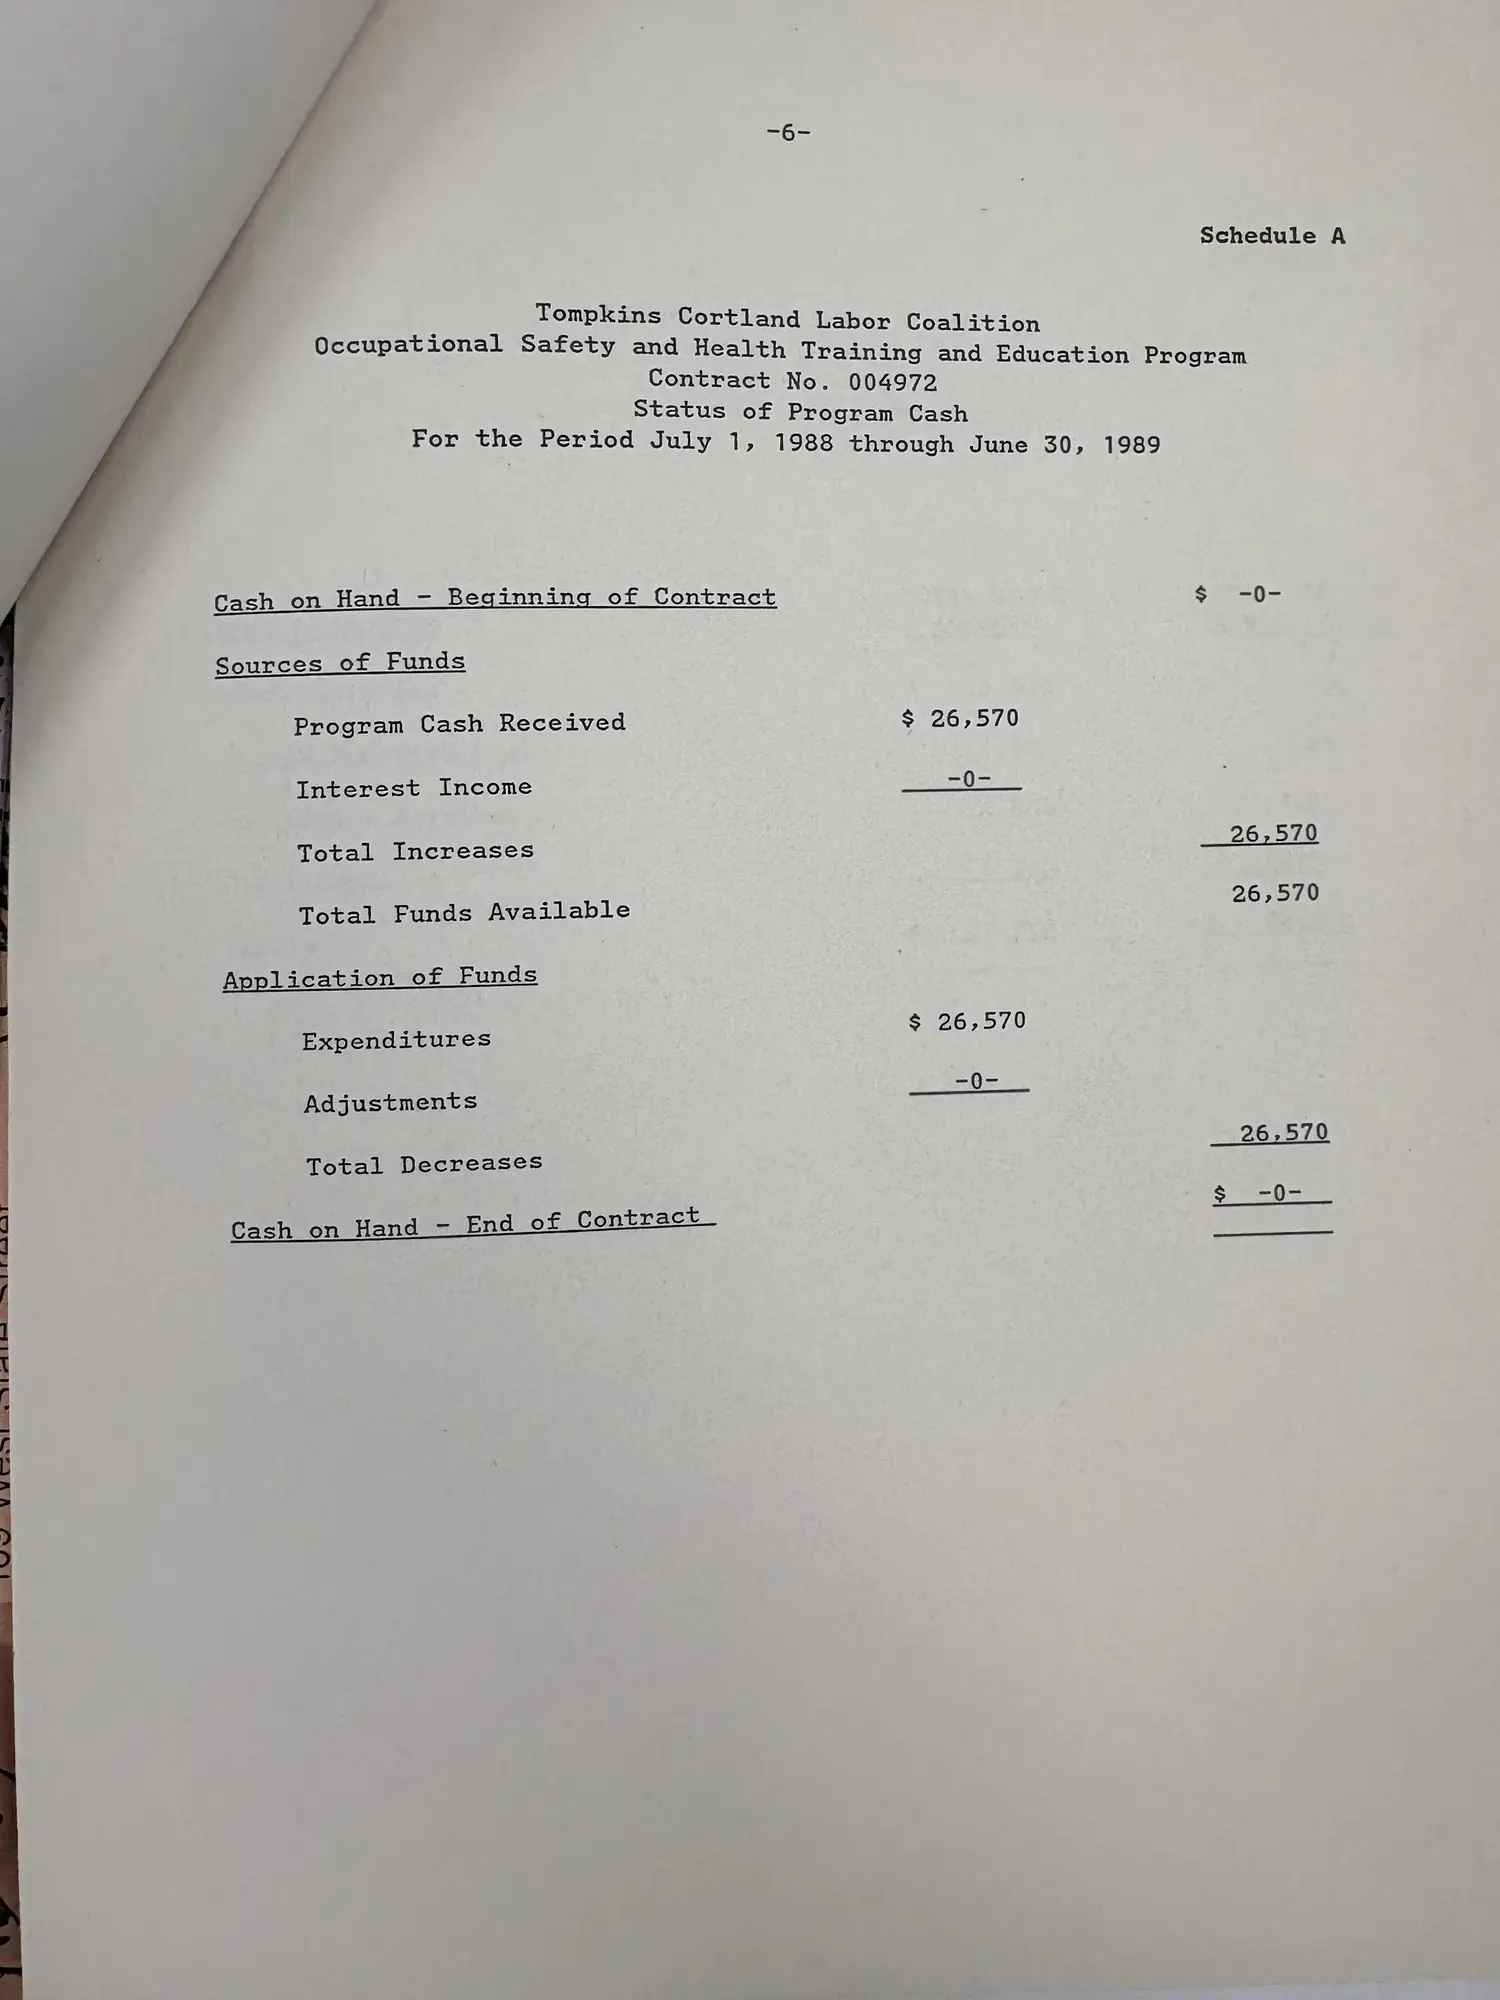
Read the page text (machine-read, contains errors)
This text was generated automatically from the photograph and has not been corrected. The image is the authoritative record.
Schedule A

Tompkins Cortland Labo atte
Occupational Safety and Health pee Pee ee eee 12
Contract No. 004972 See
Status of Program Cash
For the Period July 1, 1988 through June 30, 1989

Cash on Hand - Beginning of Contract

Sources of Funds

Program Cash Received $ 26,570

Interest Income =0=

Total Increases 26,570

Total Funds Available 26,570
Application of Funds

Expenditures $ 26,570

Adjustments see ee

Total Decreases 26,570

d - End _ of Contract

Cashvon. Hand==*En¢ oe
 (open zoom view)
Read the page text (machine-read, mostly readable)
This text was generated automatically from the photograph and has not been corrected. The image is the authoritative record.
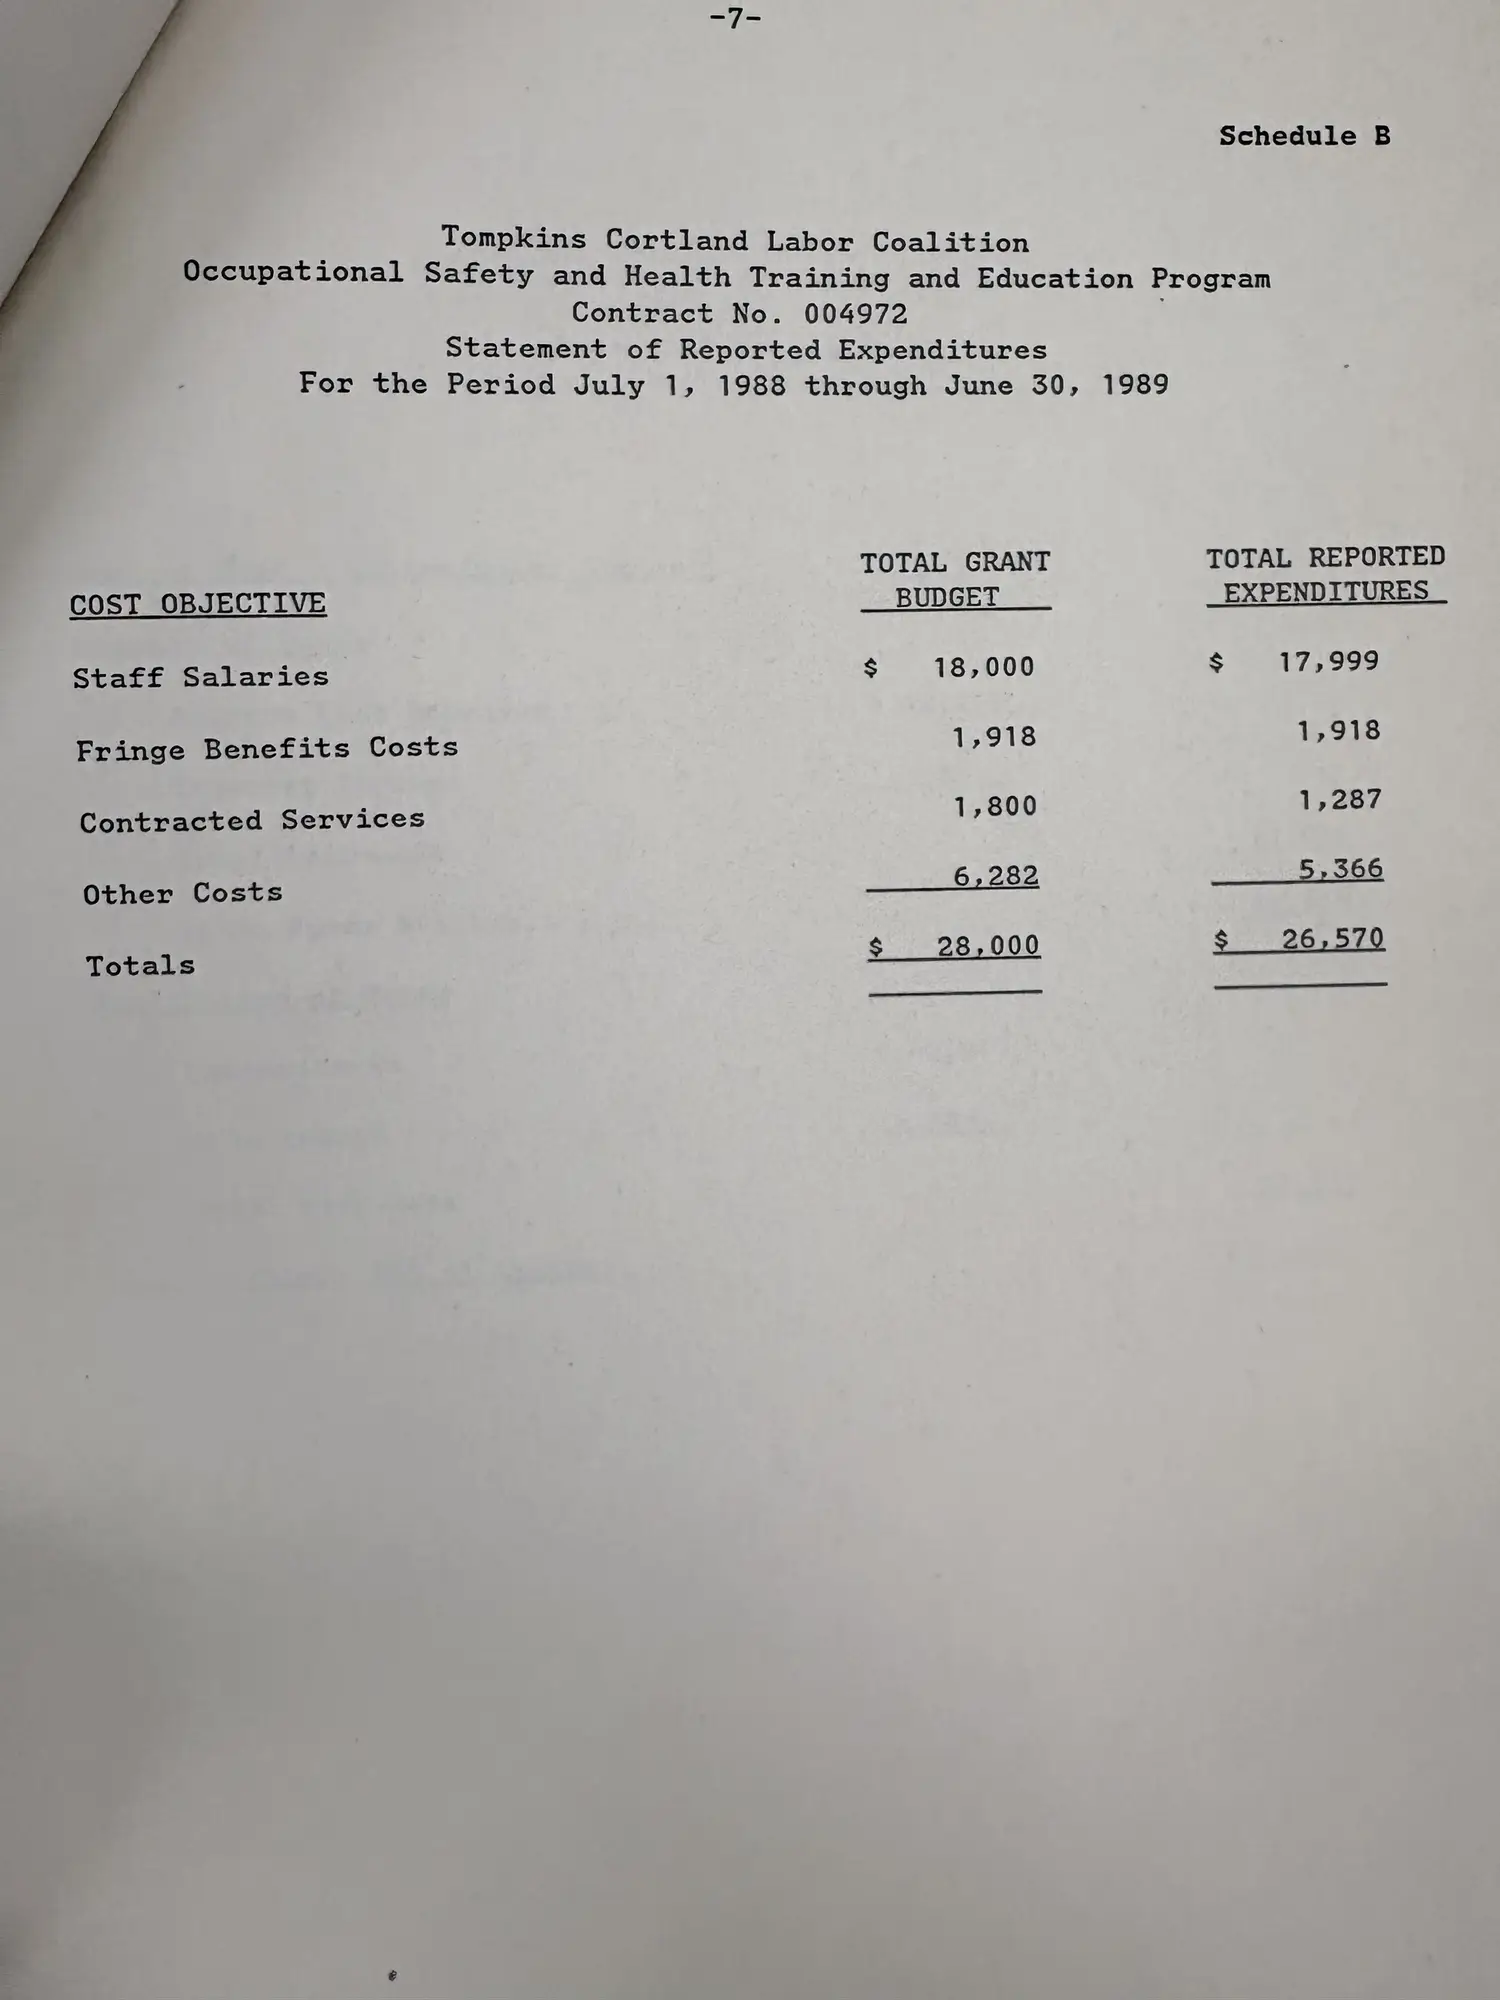
Schedule B

' Tompkins Cortland Labor Coalition
Occupational Safety and Health Training and Education Program
Contract No. 004972
Statement of Reported Expenditures
For the Period July 1, 1988 through June 30, 1989

Bah oe de

TOTAL GRANT TOTAL REPORTED
COST OBJECTIVE BUDGET EXPENDITURES
Staff Salaries $ 18,000 $ 17,999
Fringe Benefits Costs 1,918 1,918
Contracted Services 1,800 1,287
Other Costs 2 6,282 be eS SOG)

Totals

$__ 28,000

$ 26,5790
 (open zoom view)
Read the page text (machine-read, mostly readable)
This text was generated automatically from the photograph and has not been corrected. The image is the authoritative record.
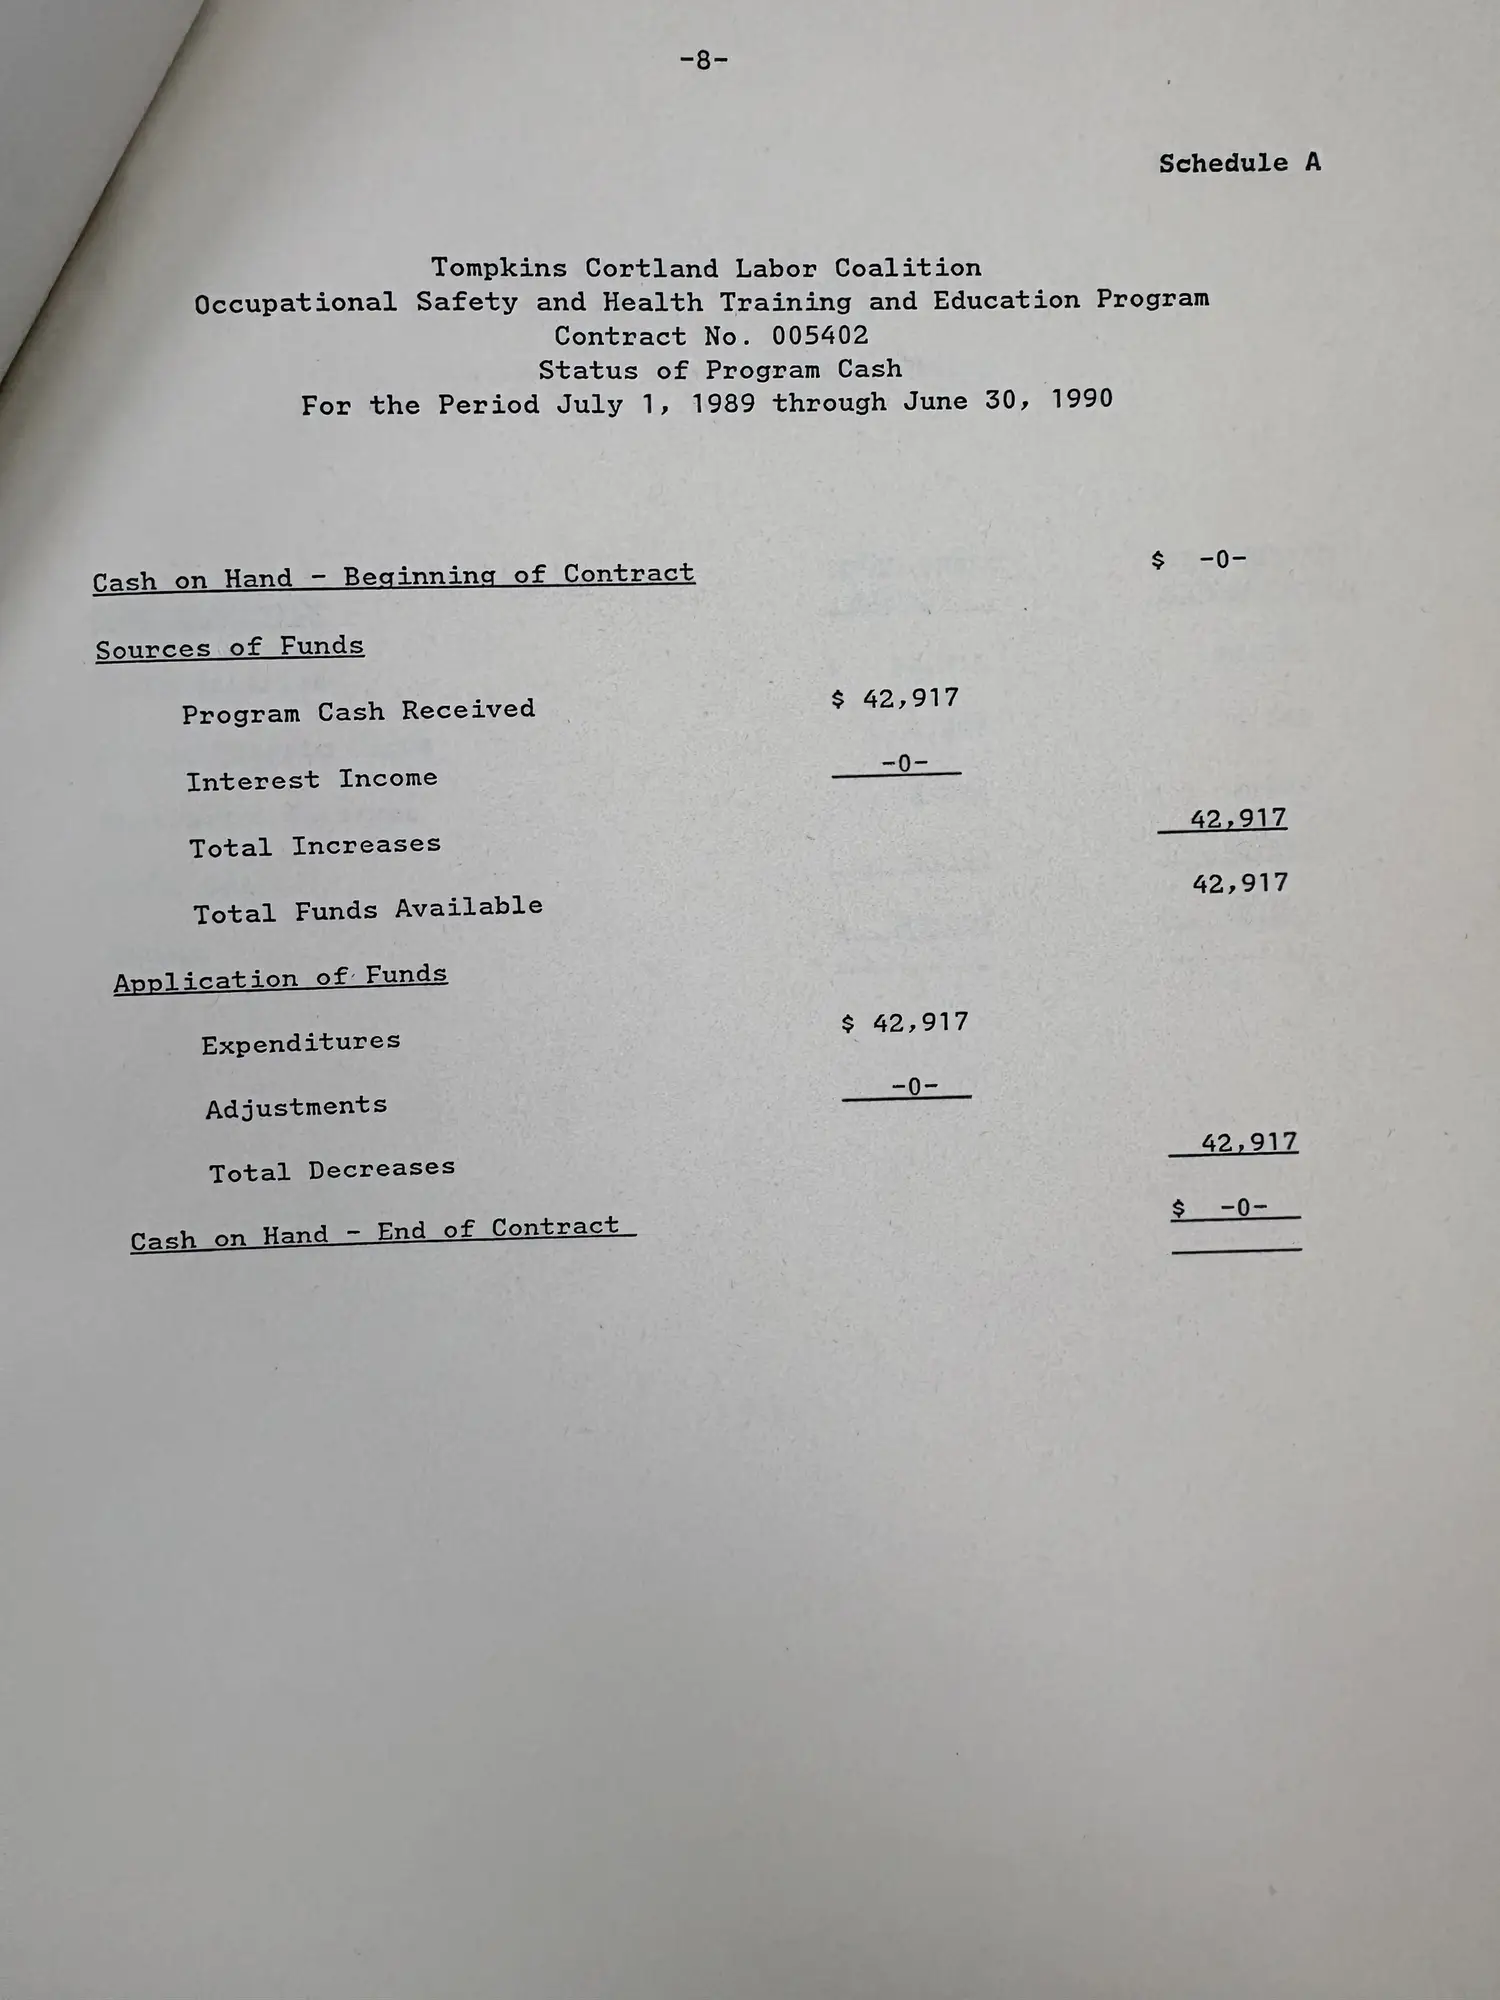
Schedule A

Tompkins Cortland Labor Coalition
Occupational Safety and Health Training and Education Program
Contract No. 005402
Status of Program Cash
For the Period July 1, 1989 through June 30, 1990

Cash on Hand - Beginning of Contract 8 Se

Sources of Funds
Program Cash Received $ 42,917
Interest Income =x)
Total Increases 42,917
Total Funds Available 42,917
Application of Funds
Expenditures $ 42,917
Adjustments -0-

Total Decreases

Cash _ on Hand — End of Contract $ -0-
 (open zoom view)
Read the page text (machine-read, mostly readable)
This text was generated automatically from the photograph and has not been corrected. The image is the authoritative record.
Schedule B

Tompkins Cortland Labor Coalition
Occupational Safety and Health Training and Education Program
Contract No. 005402
Statement of Reported Expenditures
For the Period July 1, 1989 through June 30, 1990

TOTAL GRANT TOTAL REPORTED

COST OBJECTIVE BUDGET EXPENDITURES
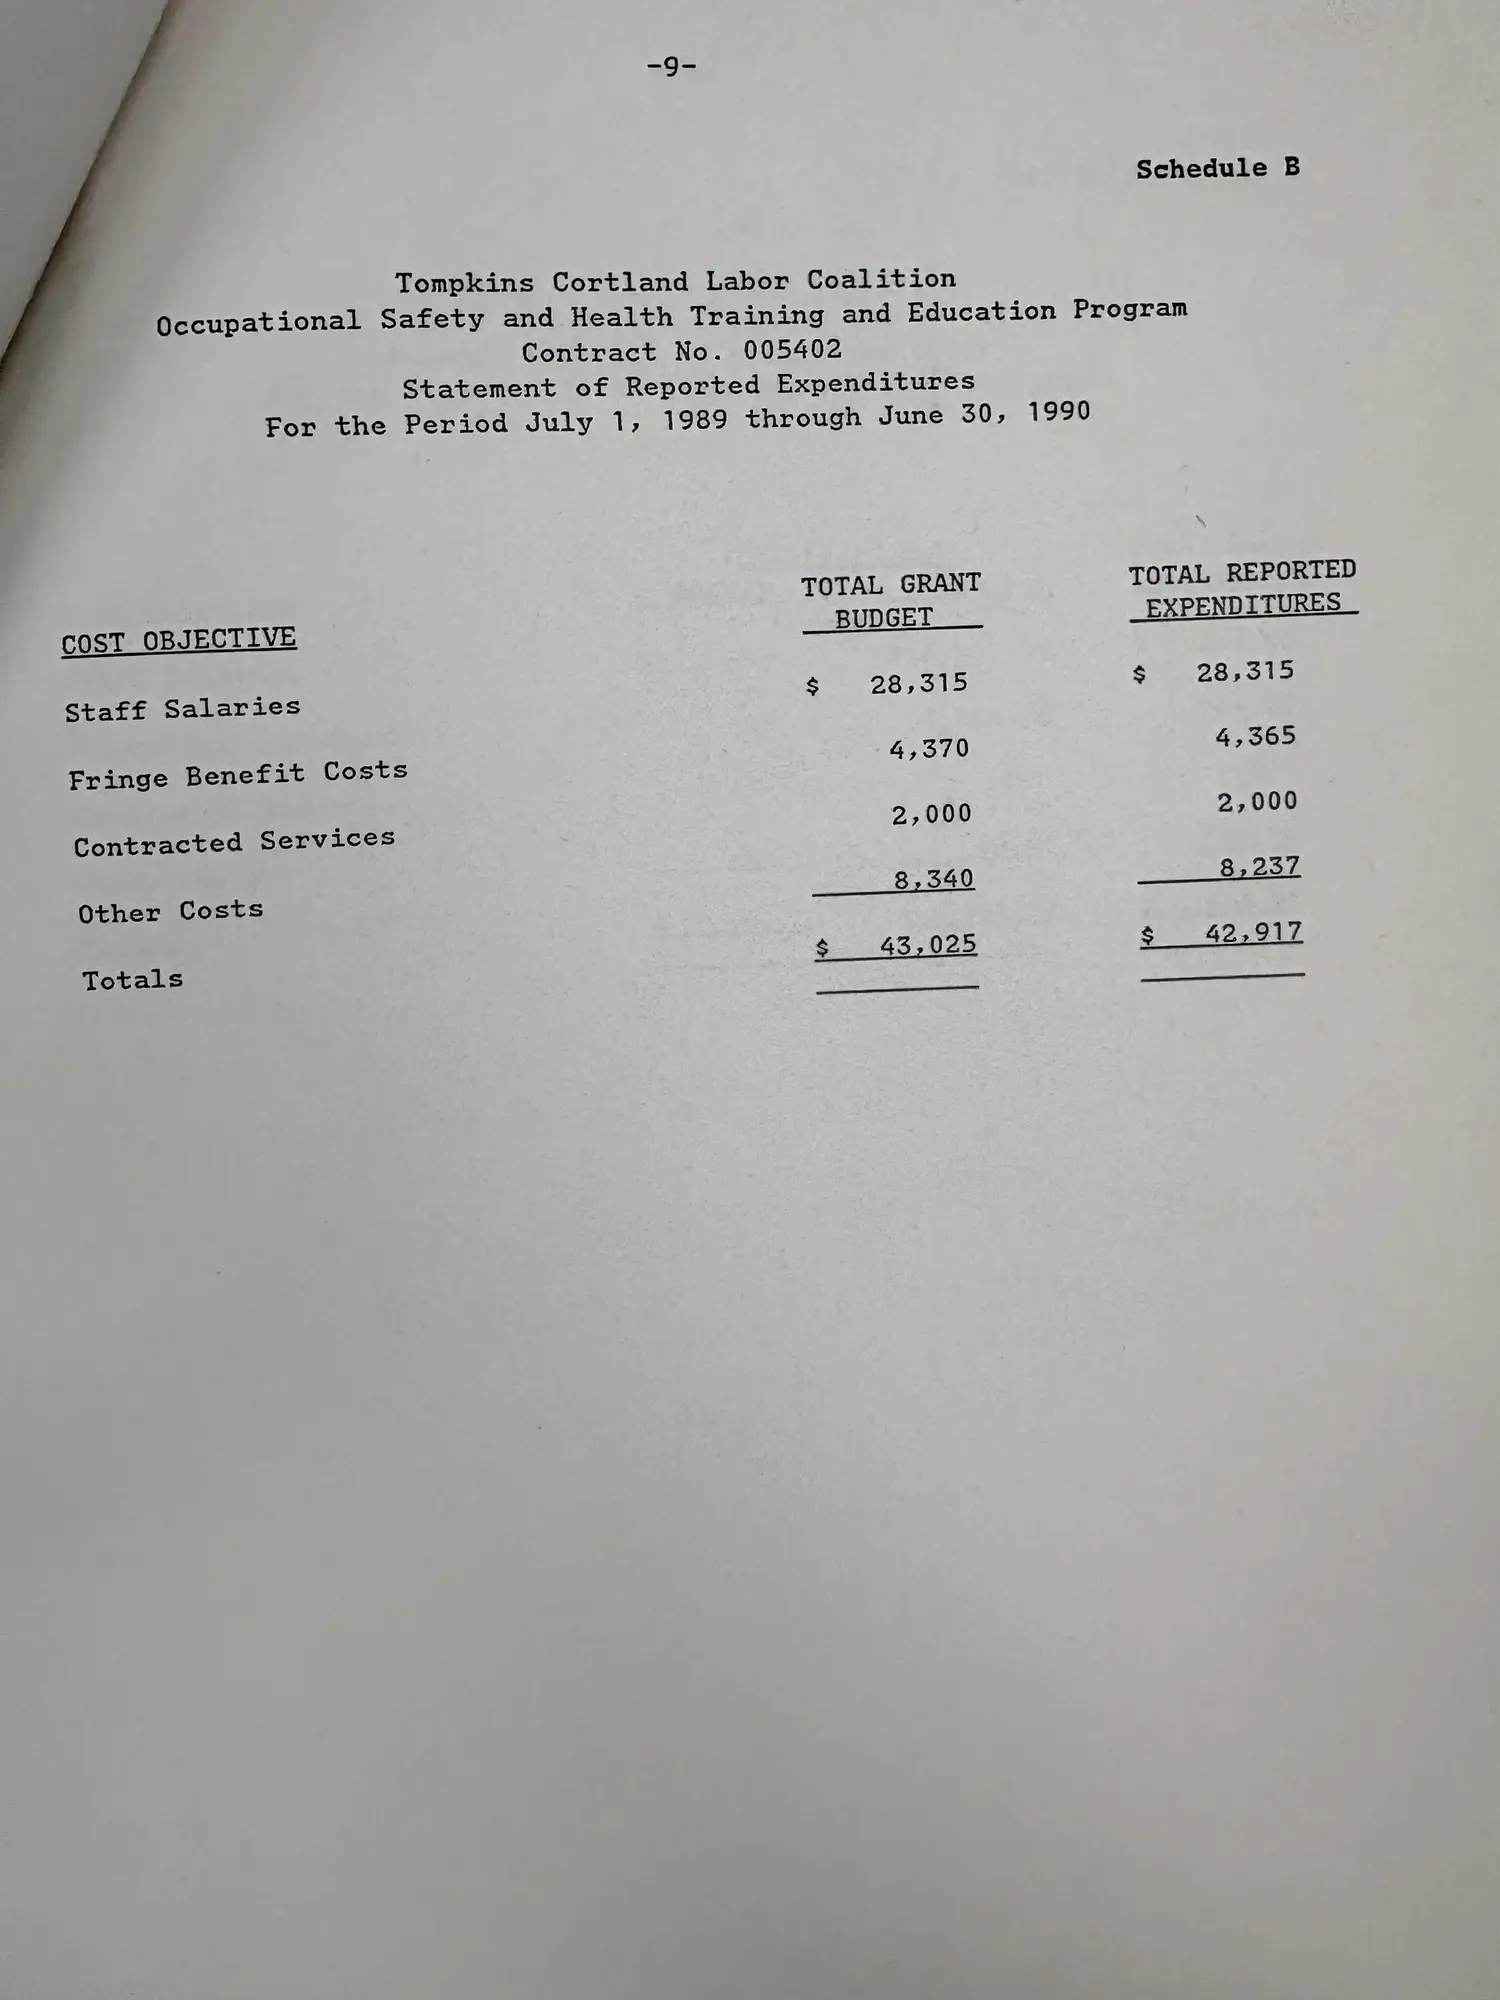
Staff Salaries $ 28,315 $ 28,315
Fringe Benefit Costs 4,370 4,365
Contracted Services 2,000 2,000

Other Costs

Totals

8,340

$ 43,025

__ 8237

$ 42,917

pn Sn
 (open zoom view)
Read the page text (machine-read, contains errors)
This text was generated automatically from the photograph and has not been corrected. The image is the authoritative record.
Auditor's Exhibit I

Tompkins Cortland Labor Coalition
Occupational Safety and Health Training and Education Program
Summary Schedule of Questioned Costs
For the Period July 1, 1988 through June 30, 1990

Contract No. Total Amount
Cost Objective —004972 _ 005402 Questioned
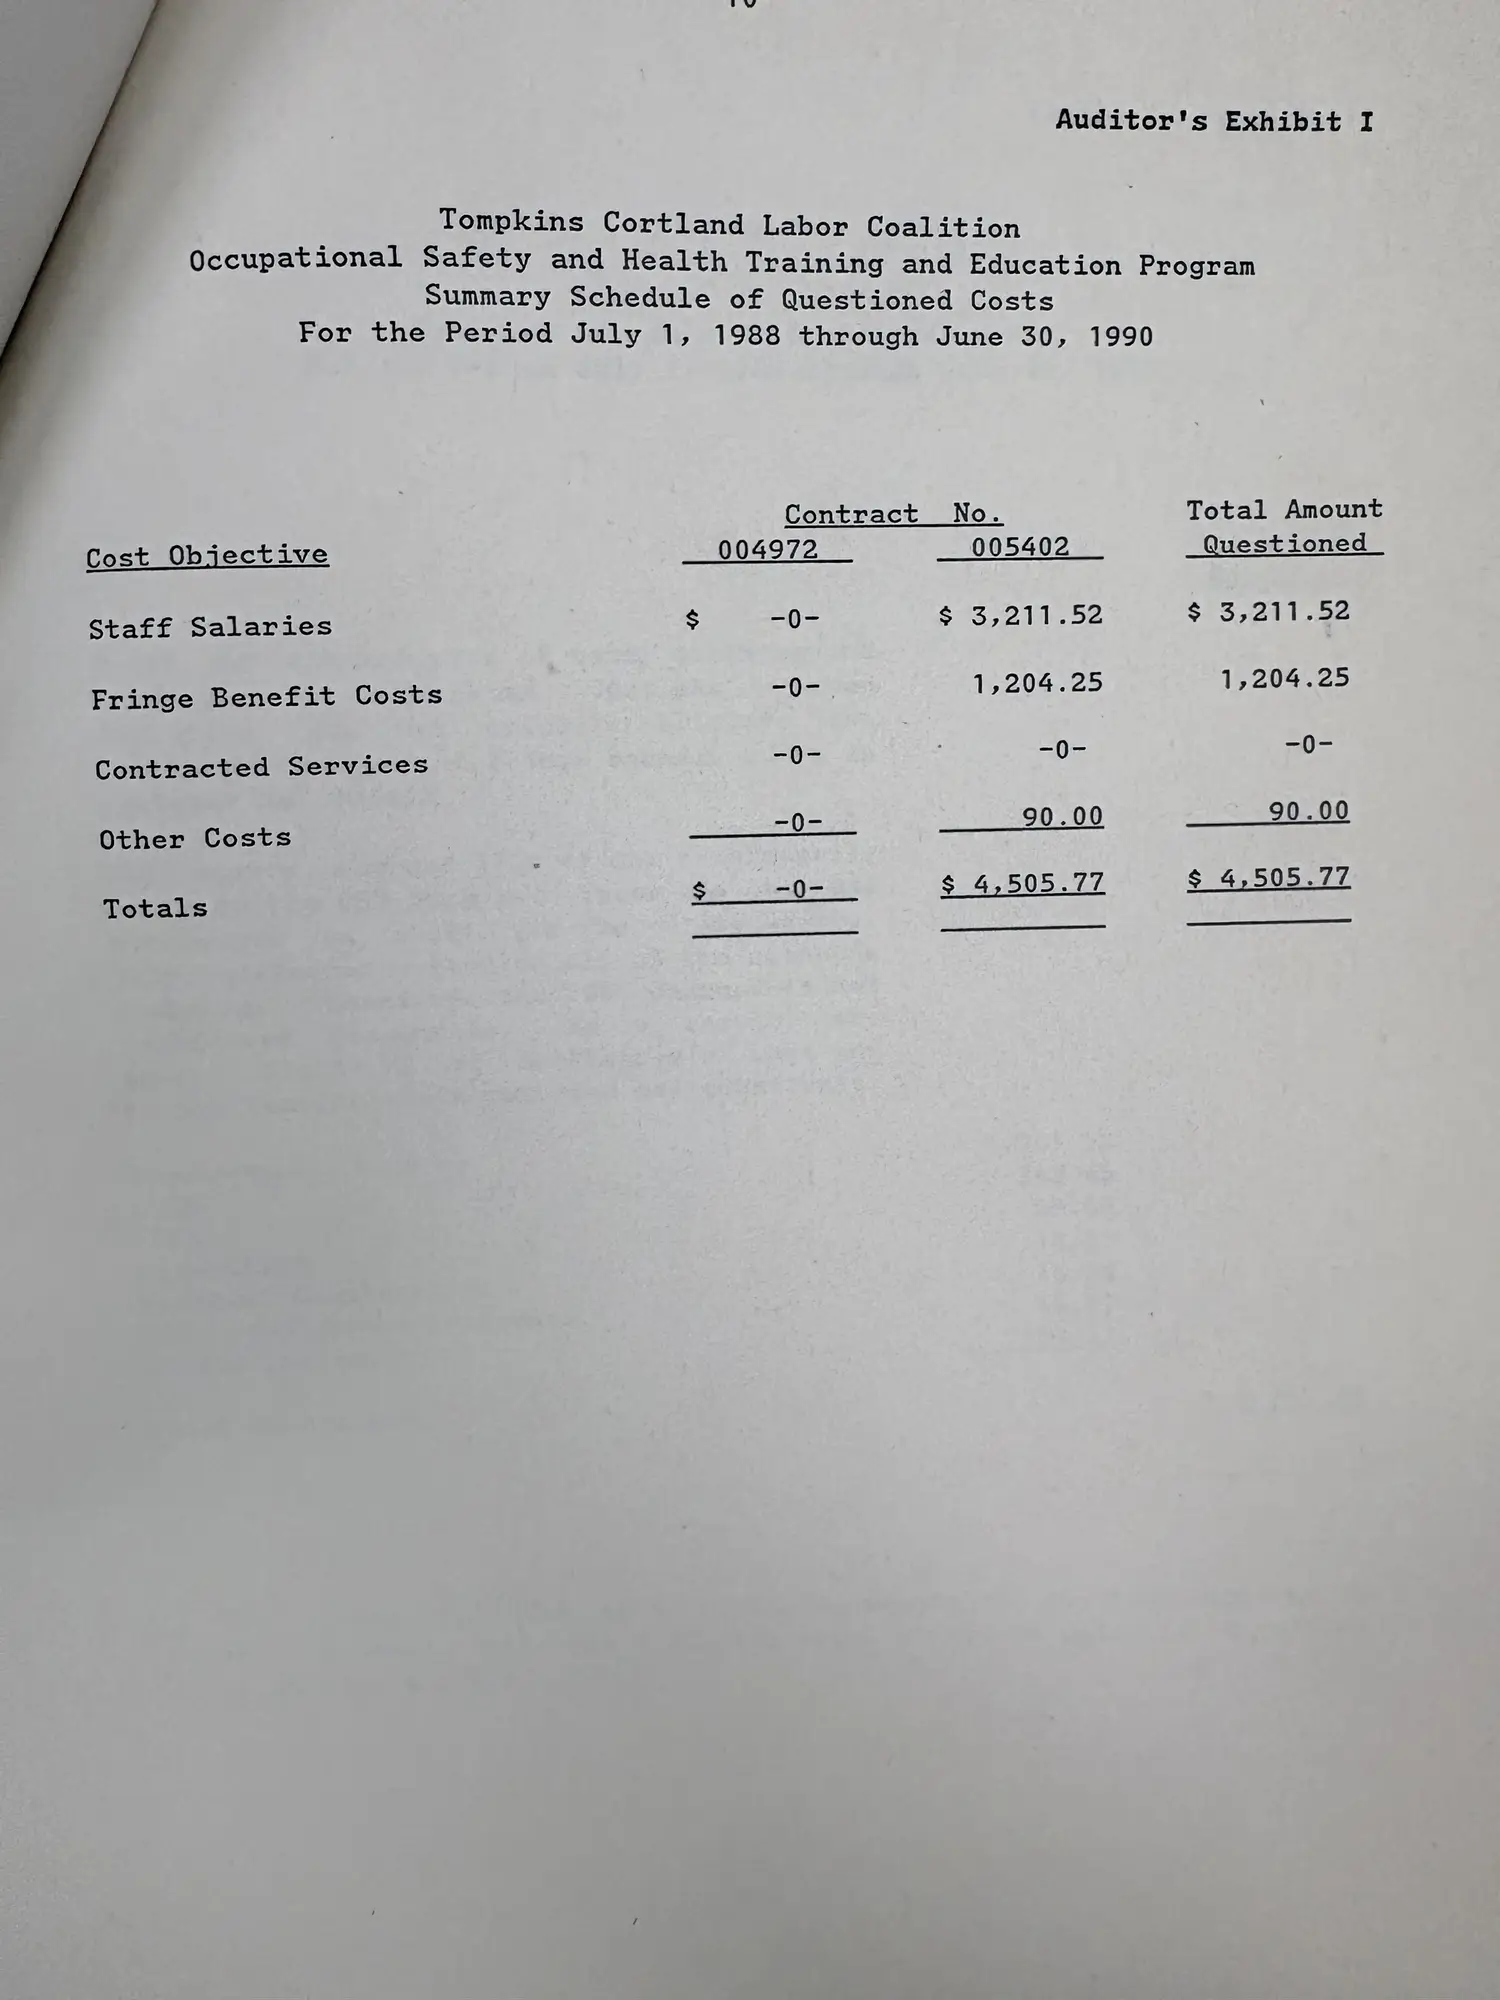
Staff Salaries $ -0- $ 3,211.52 $ 3,211.52
Fringe Benefit Costs —0- 1,204.25 1,204.25
Contracted Services -0- == 0
Other Costs recat OP oO) :200. es 390200

Totals $ a0 = $ 4,505.77 $ 4,505.77

Fe eeeeeeiemanmenene | i745 72+. 5 eerie
 (open zoom view)
Read the page text (machine-read, mostly readable)
This text was generated automatically from the photograph and has not been corrected. The image is the authoritative record.
-13-

Auditor's Exhibit I-c

Tompkins Cortland Labor iti
Occupational Safety and Health Bemis c/a eee P :
Contract No. 005402 ey en.
Detailed Schedule of Questioned Costs
For the Period July 1, 1989 through June 30, 1990

Amount
Questioned

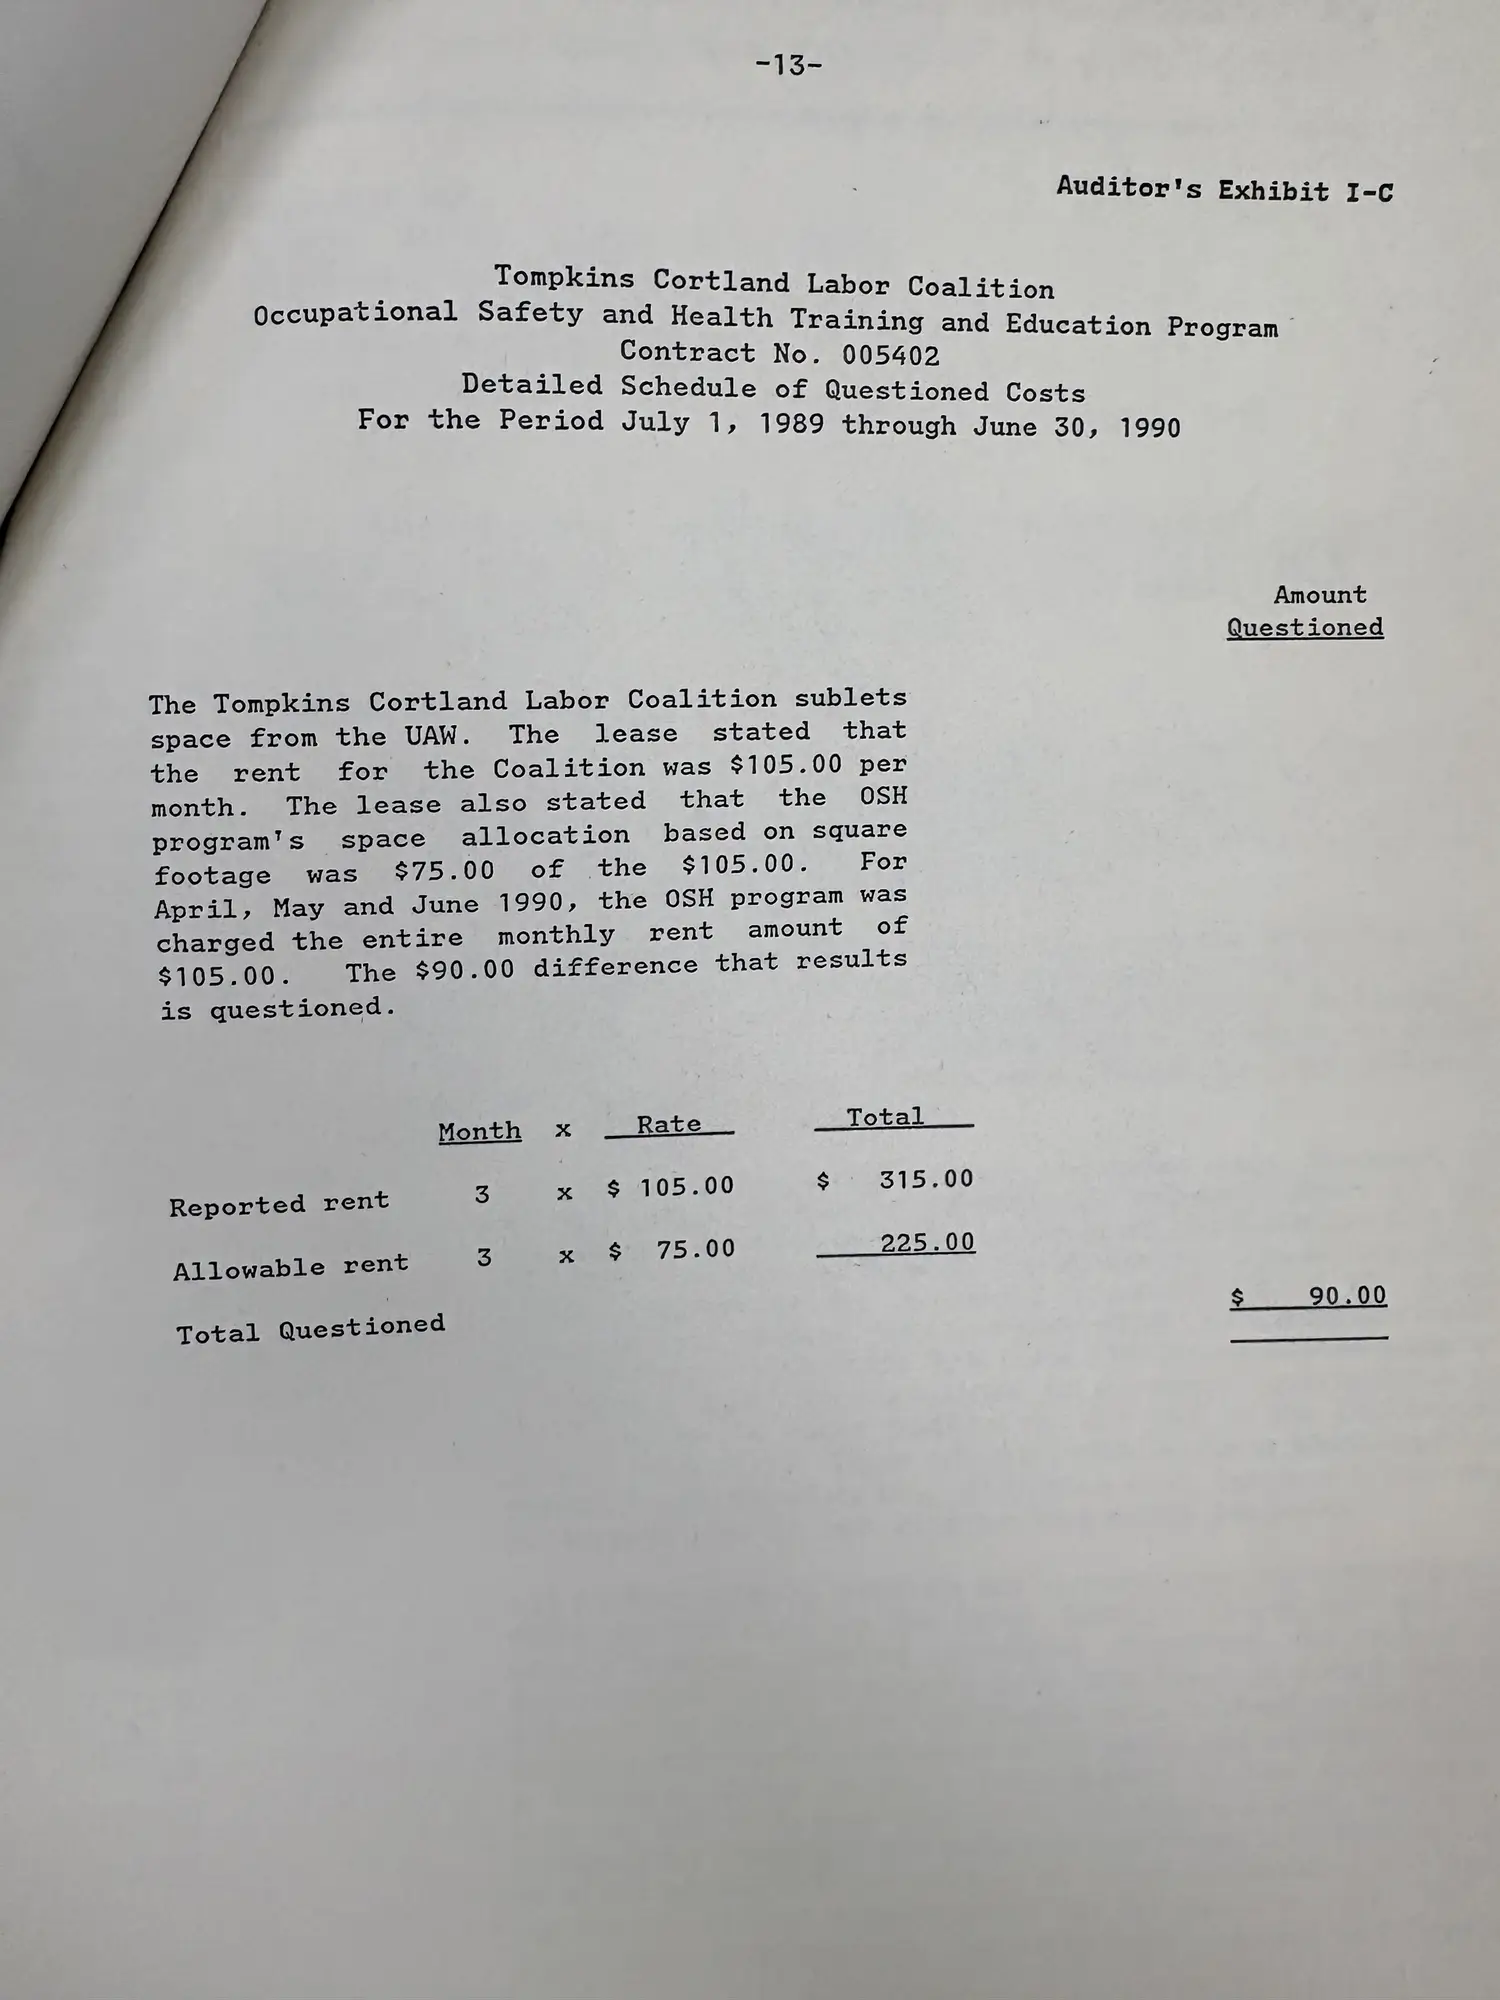
The Tompkins Cortland Labor Coalition sublets
space from the UAW. The lease stated that
the rent for the Coalition was $105.00 per
month. The lease also stated that the OSH
program’s space allocation based on square
footage was $75.00 of the $105.00. For
April, May and June 1990, the OSH program was
charged the entire monthly rent amount of
$105.00. The $90.00 difference that results
is questioned.

Month x Rate Total
Reported rent 3 x $ 105.00 $ 315.00
Allowable rent 3 x $ 75.00 225.00

Total Questioned $ 90.00
See something wrong, or recognize a person or event? Send a correction. If you hold rights in this item or think it should not be public, write to the same address.